
India Military Drones (UAS) Market Outlook 2021-2031F
Market Size, Share, Trends, Opportunities, and Competitive Analysis - Segmented by Platform Type (Medium Altitude Long Endurance and High Altitude Long Endurance, Tactical and Mini UAS, and Loitering Munitions and Combat Drones); Application (Intelligence, Surveillance and Reconnaissance, Strike and Combat, and Logistics and Others); Service (Army, Air Force, and Navy and Paramilitary); and Region
India Military Drones (UAS) Market to Reach USD 5.5 Billion by 2031, Growing at a 28% CAGR: How Large Armed Drone Orders, Indigenous Content Rules and Loitering Munitions Are Reshaping Procurement
India Military Drones (UAS) Market Overview
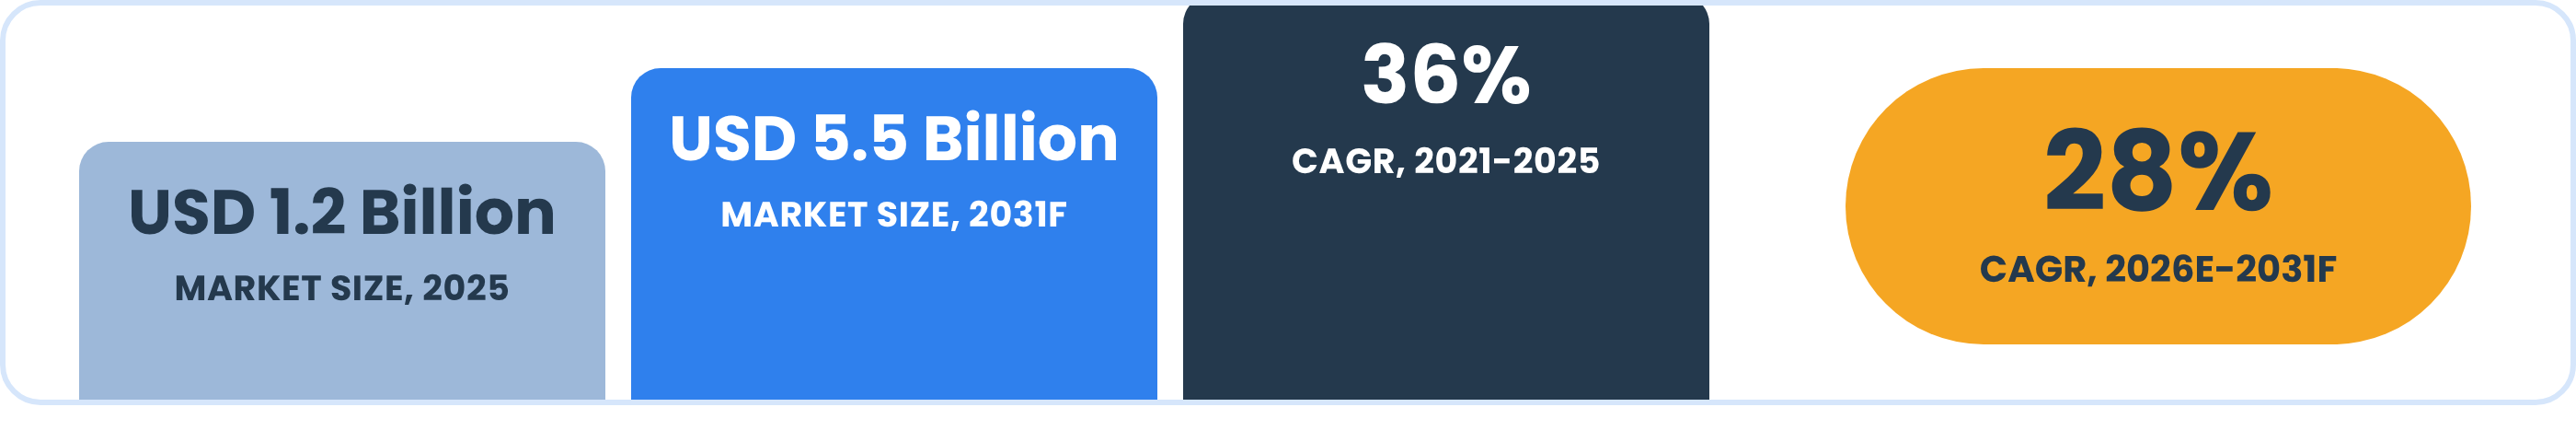
India is scaling military drone procurement across surveillance, strike and logistics roles. Neargoal Consulting estimates the market at about USD 1.2 billion in 2025, rising to USD 1.6 billion in 2026E and USD 5.5 billion by 2031, a 28% CAGR over 2026E-2031F, after a 36% CAGR over 2021-2025. The Defence Acquisition Council approved 87 armed medium altitude long endurance drones worth about USD 3.71 billion (INR 323.5 billion) in August 2025, with at least 60% indigenous content.
Key Takeaway India is pairing large imported platforms with indigenous content mandates. Suppliers that can meet the 60% content threshold and offer long-term sustainment will capture a multi-year order book that begins to deliver around 2029-30. |
India Military Drones (UAS) Market at a Glance
MARKET DEFINITION Value of Military Unmanned Aerial System Procurement, Sustainment and Services in India (USD Billion) | ||
BASE YEAR / ESTIMATED YEAR 2025 / 2026E | FORECAST PERIOD 2027F-2031F | |
MARKET SIZE, 2025 USD 1.2 Billion | MARKET SIZE, 2026E USD 1.6 Billion | |
MARKET SIZE, 2031F USD 5.5 Billion | RECORDED CAGR, 2021-2025 36% | |
FORECAST CAGR, 2026E-2031F 28% | ARMED MALE DRONE APPROVAL 87 Drones, About USD 3.71 Billion | |
INDIGENOUS CONTENT REQUIREMENT At Least 60% | SUPPORT PACKAGE USD 1.26 Billion Over 10 Years | |
FIRST DELIVERIES EXPECTED 2029-30 | LEADING PLATFORM TYPE Medium Altitude Long Endurance | |
FASTEST-GROWING SEGMENT Loitering Munitions and Combat Drones | KEY CONSTRAINTS Engine and Sensor Dependence, Certification and Airspace Rules | |
Source: Neargoal Consulting Analysis | ||
Market Outlook
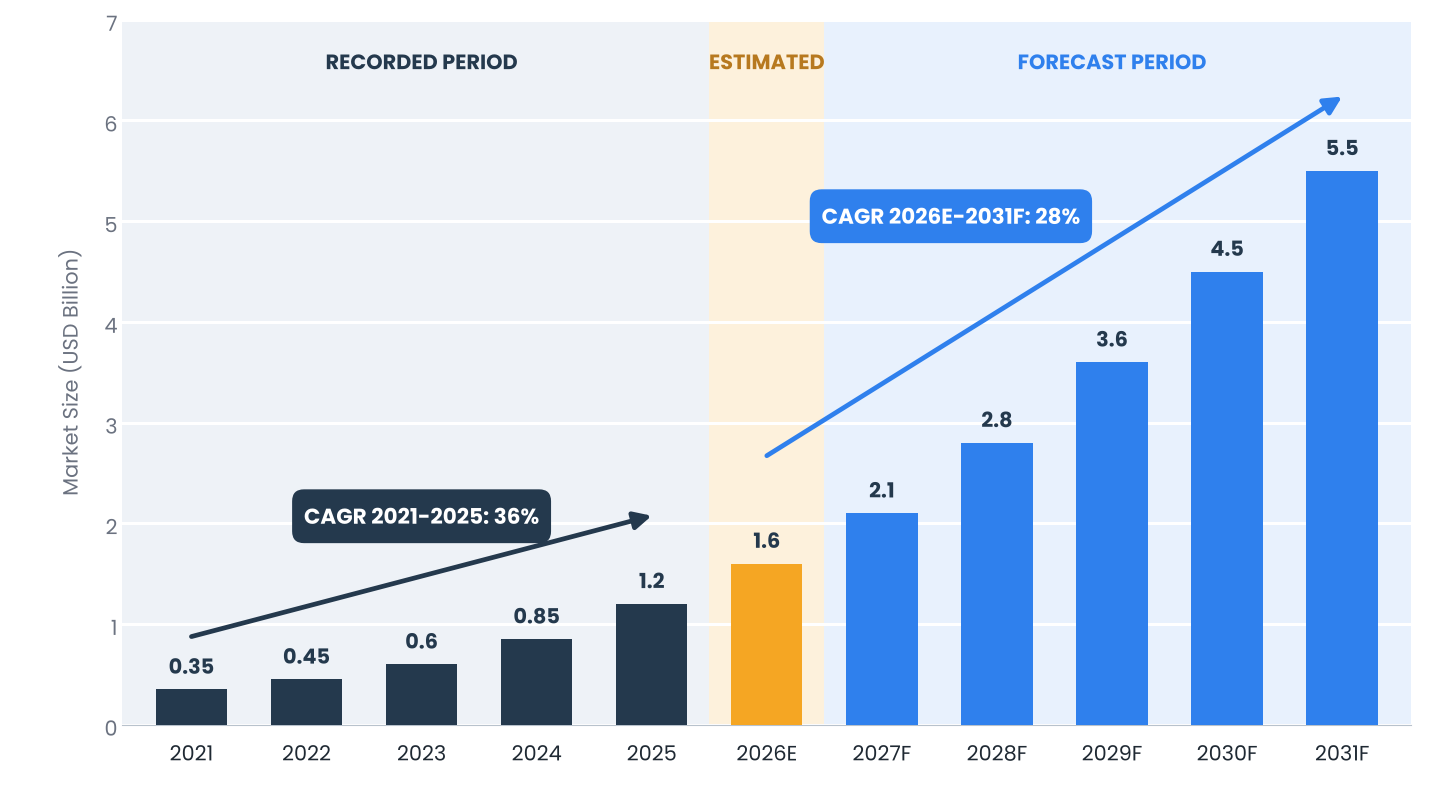
Our study estimates the market will grow at a 28% forecast CAGR (2026E-2031F) from USD 1.6 billion in 2026E, after a 36% CAGR over 2021-2025. The base case assumes that development and contracting of the 87-drone program proceeds through 2027F, that deliveries begin around 2029-30, and that smaller tactical drones and loitering munitions grow faster through emergency and fast-track procurement.
Figure 1: India Military Drones (UAS) Market Size, 2021-2031F (USD Billion)
Source: Neargoal Consulting Analysis
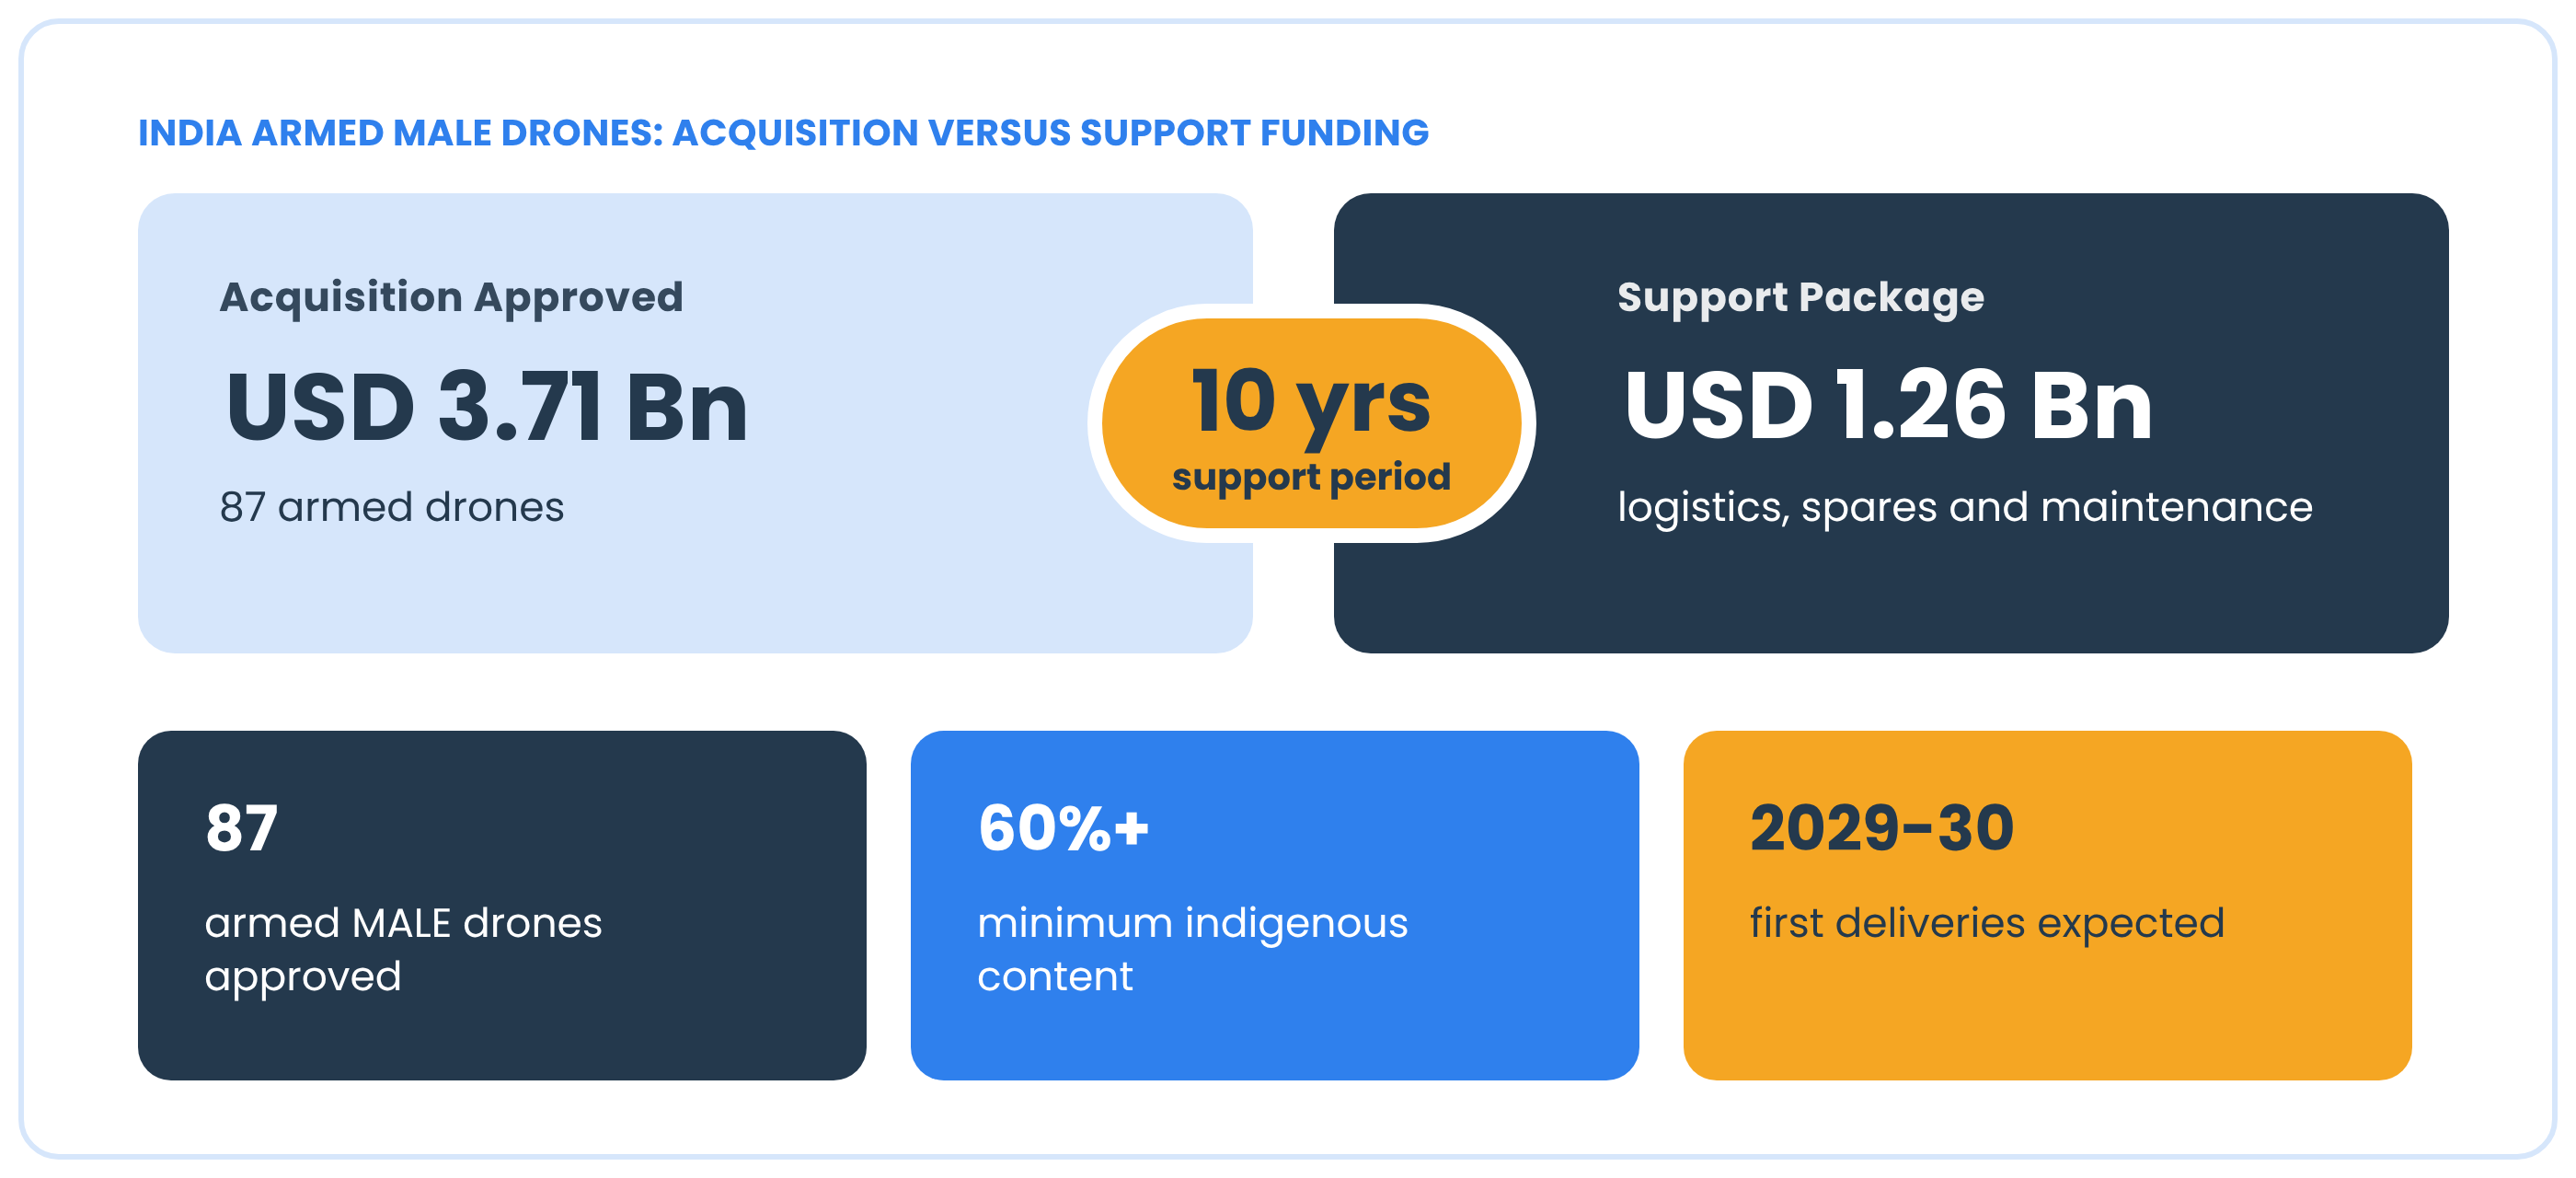
Figure 2: India Armed MALE Drones: Acquisition Versus Support Funding
Source: Neargoal Consulting Analysis
Market Dynamics
Growth Drivers
- Large Armed Drone Program. The 87-drone approval is described as one of the largest indigenous drone acquisitions to date, with an additional USD 1.26 billion (INR 110 billion) for a 10-year logistics and maintenance package.
- Indigenization Policy. Programs are structured under the Make in India framework with at least 60% indigenous content, which pulls domestic suppliers into the supply chain.
- Persistent Surveillance Needs. Armed forces require long-endurance surveillance and strike along the northern and western borders.
Restraints
- Dependence on Imported Engines and Sensors. Foreign original equipment manufacturers supply key propulsion and payload components.
- Certification and Airspace Rules. Armed unmanned systems require airworthiness certification and airspace integration.
- Long Delivery Timelines. Deliveries of the large program are not expected until 2029-30, which delays revenue.
Opportunities
- Domestic Subsystems. Engines, sensors, datalinks and ground stations for indigenous content.
- Loitering Munitions and Tactical Drones. Fast-track procurement for operational needs.
- Sustainment and Training. Long-term maintenance, spares and training contracts.
- Counter-Drone and Autonomy Software. Mission software and swarm control add value to platforms.
Policy and Regulatory Landscape
Indian military drone procurement is governed by the Defence Acquisition Council, which approves programs under the Defence Acquisition Procedure and prioritizes the Make in India framework and the Buy (Indian-IDDM) category. Indigenous content thresholds, offset obligations and negative import lists for certain items shape supplier choices. Civil drone rules and airspace integration affect testing and deployment. The full report assesses how procurement categories and content rules affect timing and winners.
Segment Insights
The full report quantifies every segment; the highlights below cover Platform Type, Application, and Service.
By Platform Type
Medium altitude long endurance platforms take the largest share of value, while loitering munitions and combat drones grow fastest.
By Application
Intelligence, surveillance and reconnaissance holds the largest share in 2025, but strike and combat missions are expected to grow fastest as armed platforms enter service. Logistics and other roles add smaller volumes. Our analysis expects strike and combat to take a growing share of procurement through 2031F.
By Service
- Army. The largest user of tactical and mini systems along the borders.
- Air Force. Long-endurance and combat platforms.
- Navy and Paramilitary. Maritime surveillance and border and internal security roles.
Geographic Insights
Demand follows operational theaters and defense industrial clusters.
- Northern Border and Ladakh. High-altitude surveillance and overwatch requirements.
- Western Front. Cross-border surveillance and strike missions.
- Defence Corridors. Uttar Pradesh and Tamil Nadu defence industrial corridors host manufacturing.
- Coastal and Island Territories. Maritime surveillance requirements.
Competitive Landscape
Key participants include Hindustan Aeronautics, Bharat Electronics, Defence Research and Development Organisation labs, Tata Advanced Systems, Adani Defence, Larsen and Toubro, General Atomics and Israel Aerospace Industries. Competition rests on indigenous content, technology transfer and sustainment. Large programs pair foreign original equipment manufacturers with Indian partners.
Hindustan Aeronautics | Bharat Electronics | Tata Advanced Systems | Adani Defence |
Larsen and Toubro | General Atomics | Israel Aerospace Industries | Zen Technologies |
Key Developments, 2025-2026
- August 2025. The Defence Acquisition Council approves 87 armed medium altitude long endurance drones worth about USD 3.71 billion (INR 323.5 billion).
- August 2025. An additional USD 1.26 billion (INR 110 billion) is sanctioned for a 10-year logistics, spares and maintenance package.
- 2026-2027. Development and contracting of the 87-drone program is expected to progress.
- 2029-30. First deliveries of the 87-drone program are expected.
What This Means for Decision-Makers
- Platform Makers: Secure Indian partners early to meet the 60% indigenous content threshold.
- Subsystem Suppliers: Position engines, sensors and datalinks for domestic content.
- Armed Forces: Balance long-endurance platforms with fast-track tactical systems.
- Investors: Track contract signing and delivery milestones, not approvals.
About the Report
Table 1: India Military Drones (UAS) Market: Report Coverage
Coverage Area | What the Report Covers |
Market Size and Forecast | Value (USD Billion) and Order Views, 2021-2031F |
Segmentation | Platform Type, Application and Service |
Geography | Northern Border, Western Front, Defence Corridors and Coastal Areas |
Competition | Platform Makers, Subsystem Suppliers and Program Tracking |
Policy and Constraints | Procurement Categories, Indigenous Content and Airspace Rules |
Outlook and Recommendations | Opportunity Assessment and Guidance by Stakeholder |
Source: Neargoal Consulting Analysis | |
The research report, India Military Drones (UAS) Market Outlook 2021-2031F - Market Size, Share, Trends, Opportunities, and Competitive Analysis - Segmented by Platform Type (Medium Altitude Long Endurance and High Altitude Long Endurance, Tactical and Mini UAS, and Loitering Munitions and Combat Drones); Application (Intelligence, Surveillance and Reconnaissance, Strike and Combat, and Logistics and Others); Service (Army, Air Force, and Navy and Paramilitary); and Region, covers procurement, sustainment and services for military unmanned aerial systems in India, with a 2025 base year, a 2026E estimate and a 2027F-2031F forecast. It excludes civil and commercial drones and counter-drone systems. Market estimates and projections are based on Neargoal Consulting’s proprietary research methodology, exhaustive primary and secondary research.
For questions about report coverage, methodology, suitability, etc.
For requirements beyond the published report