
UK GLP-1 Weight-Loss Drugs Market Outlook 2021-2031F
Market Size, Share, Trends, Opportunities, and Competitive Analysis - Segmented by Molecule (Semaglutide, Tirzepatide, and Others); Channel (Private Online and Retail Pharmacies, NHS Specialist Services, and NHS Primary Care); Route of Administration (Injectable, and Oral); and Region
UK GLP-1 Weight-Loss Drugs Market to Reach USD 8.4 Billion by 2031, Growing at a 17% CAGR: How Private Demand, NHS Rollout and Falling Prices Are Reshaping Access to Weight Management
USD 2.5 Billion MARKET SIZE, 2025 | USD 8.4 Billion MARKET SIZE, 2031F | |
USD 3.8 Billion MARKET SIZE, 2026E | 17% CAGR, 2026E-2031F |
UK GLP-1 Weight-Loss Drugs Market Overview
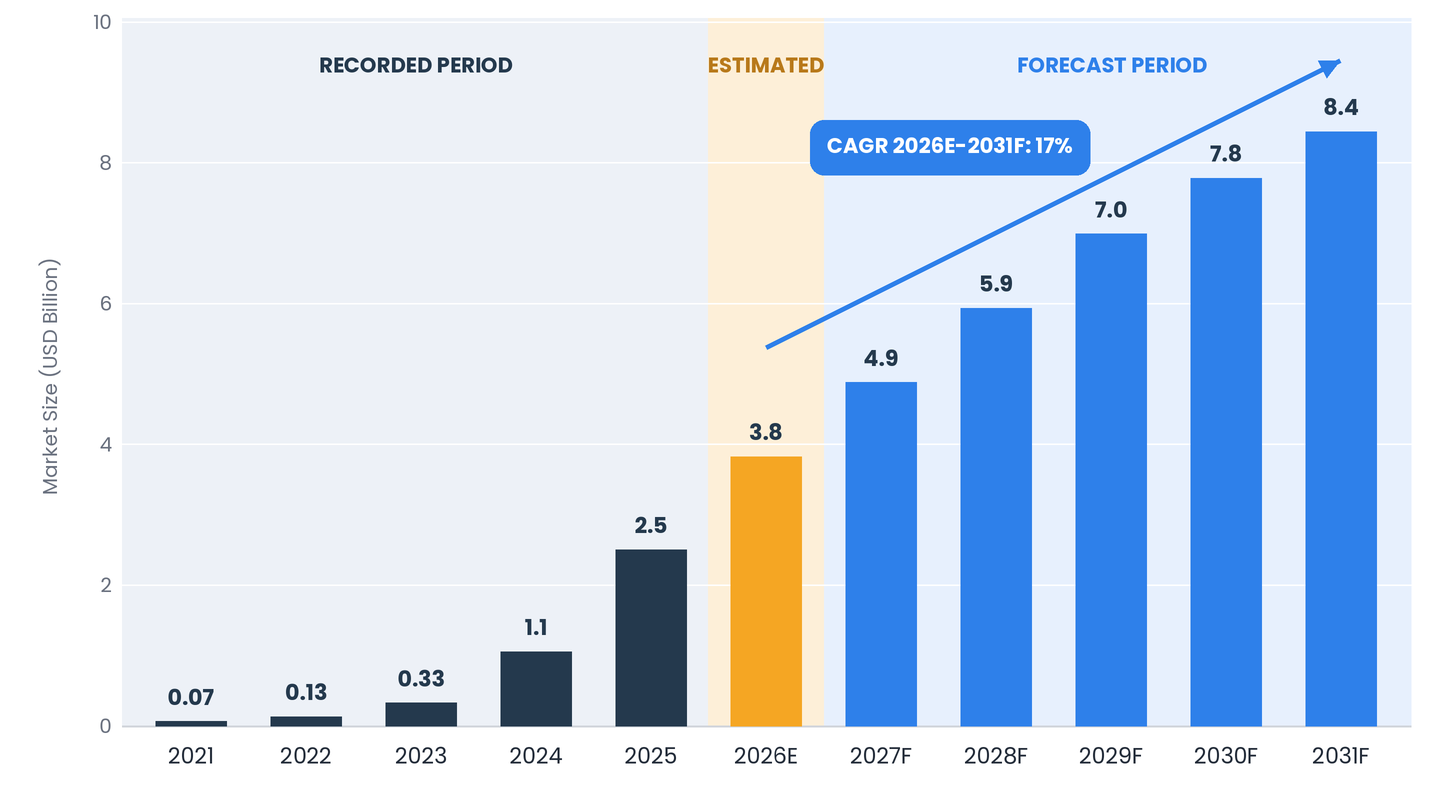
The UK has become one of Europe’s most active markets for GLP-1 weight-loss drugs, driven by private demand and a phased NHS rollout. Neargoal Consulting estimates market value at about USD 2.5 billion in 2025, rising to USD 3.8 billion in 2026E and USD 8.4 billion by 2031, a 17% CAGR over 2026E-2031F. An estimated 1.5 million people used weight-loss medication in March 2025, mostly through private pharmacies, while NICE (National Institute for Health and Care Excellence) has recommended Mounjaro on the NHS for people with a BMI of at least 35 and a weight-related condition, with access phased in over 12 years.
Key Takeaway Growth will shift from private self-pay to a mix of private and NHS-funded treatment, with lower unit prices offsetting higher volumes. Suppliers and pharmacies that manage price, adherence and clinical safeguards will hold their position as access widens. |
UK GLP-1 Weight-Loss Drugs Market at a Glance
MARKET DEFINITION Value of Prescription GLP-1 Medicines Dispensed for Weight Management in the UK, Private and NHS (USD Billion) | ||
BASE YEAR / ESTIMATED YEAR 2025 / 2026E | FORECAST PERIOD 2027F-2031F | |
MARKET SIZE, 2025 USD 2.5 Billion | MARKET SIZE, 2026E USD 3.8 Billion | |
MARKET SIZE, 2031F USD 8.4 Billion | FORECAST CAGR, 2026E-2031F 17% | |
ESTIMATED USERS, MARCH 2025 About 1.5 Million People | TYPICAL PRIVATE MONTHLY COST, 2026 USD 198-330 | |
NHS ROLLOUT OF MOUNJARO Phased Over 12 Years | NICE THRESHOLD FOR MOUNJARO BMI of 35 or Above Plus a Weight-Related Condition | |
LEADING CHANNEL Private Pharmacies | FASTEST-GROWING SEGMENT NHS Primary Care | |
KEY CONSTRAINTS Price, NHS Capacity and Treatment Duration | ||
Source: Neargoal Consulting Analysis | ||
Market Outlook
Our study estimates the market will grow at a 17% forecast CAGR (2026E-2031F) from USD 3.8 billion in 2026E, after rapid expansion from a very small base over 2021-2025. The base case assumes NHS primary care access widens in step with the phased rollout, private volumes keep growing at lower prices, and treatment durations lengthen. A survey by the National Pharmacy Association in July 2025 found that 21% of adults had tried to access weight-loss medication through an in-person or online pharmacy in the past year, rising to 35% of those aged 16-34.
Figure 1: UK GLP-1 Weight-Loss Drugs Market Size, 2021-2031F (USD Billion)
Source: Neargoal Consulting Analysis
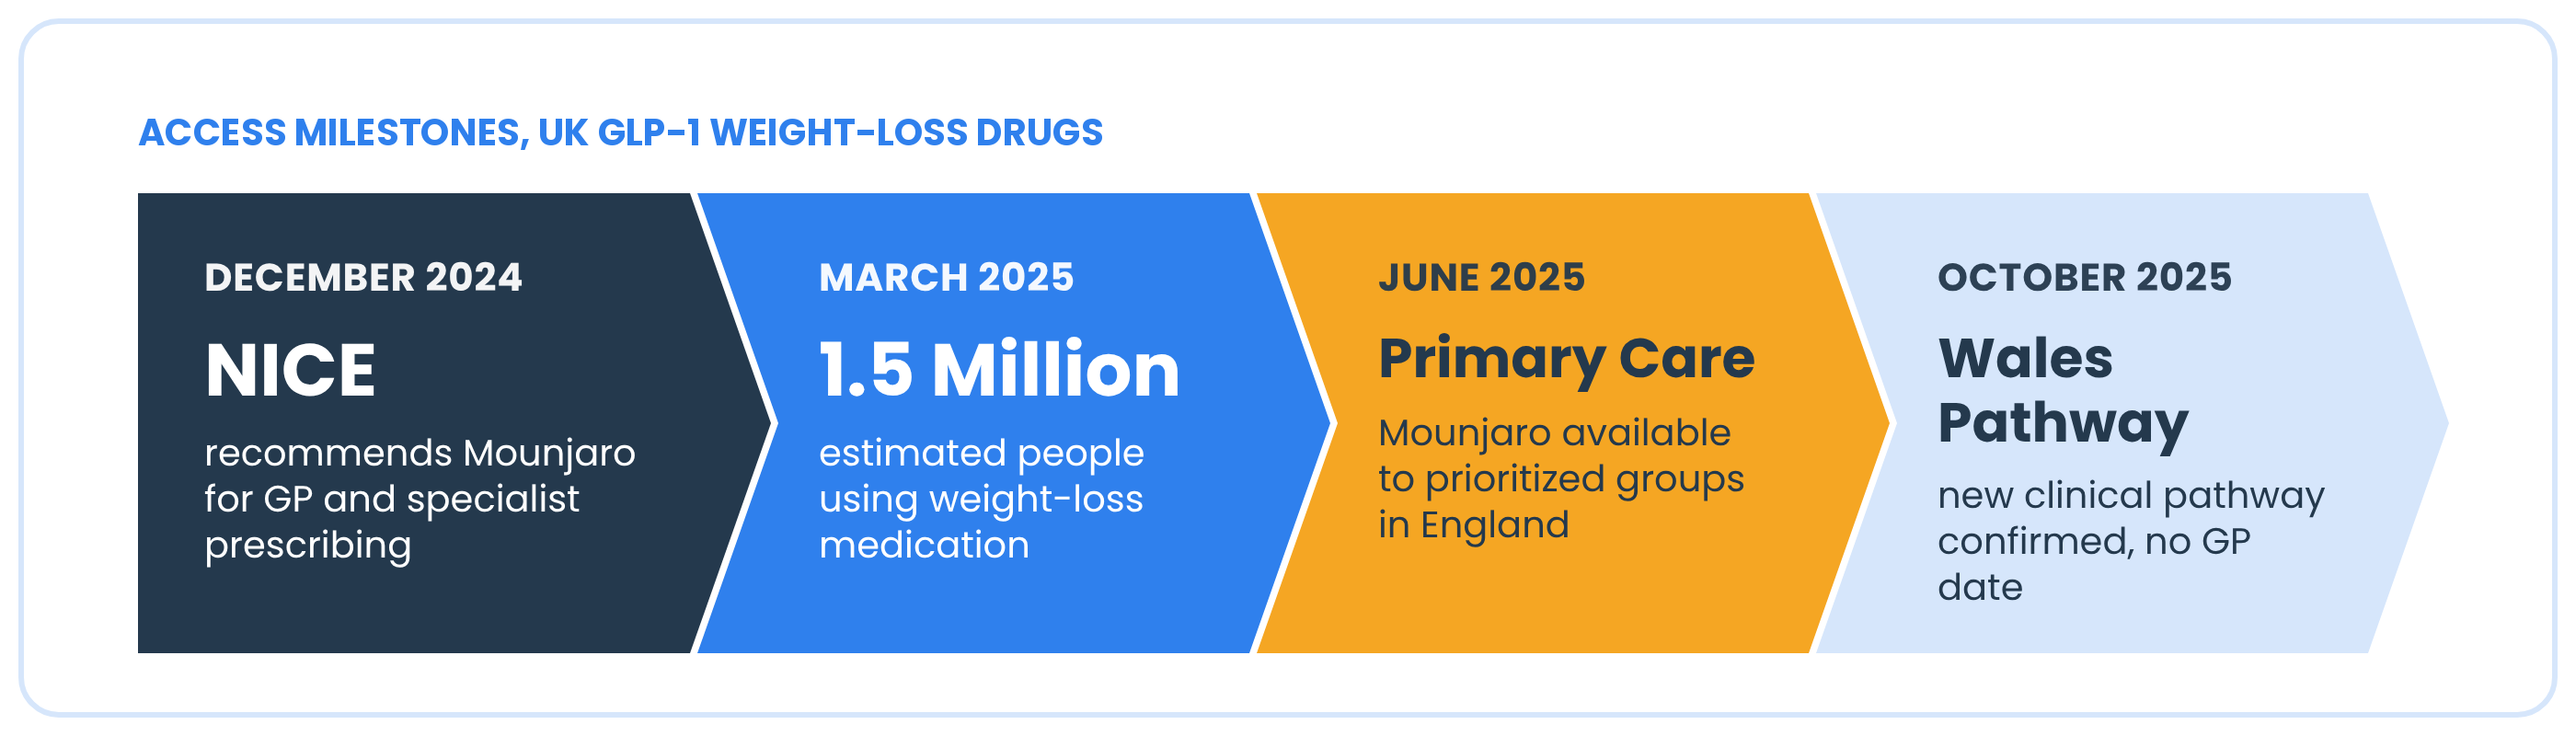
Figure 2: UK GLP-1 Weight-Loss Drugs Access Milestones
Source: Neargoal Consulting Analysis
Market Dynamics
Growth Drivers
- Private Demand and Online Access. Typical private costs of USD 198-330 (GBP 150-250) a month and online prescribing have made treatment available without NHS referral, with the weight management market reported to grow 24.6% a month from October 2024.
- NHS Rollout. NICE recommended Mounjaro in December 2024 for prescribing by GPs as well as specialist services, and NHS England began primary care prescribing to prioritized groups from June 2025 under a 12-year phased plan.
- Clinical Efficacy and Awareness. Semaglutide (Wegovy) and tirzepatide (Mounjaro) are licensed for weight management, and public awareness has risen sharply.
Restraints
- Cost and Price Rises. Eli Lilly raised its UK list prices for Mounjaro in 2025, increasing costs for private users.
- NHS Capacity and Eligibility. Wegovy and Saxenda are available only through specialist services, and the NHS plan phases eligibility over 12 years.
- Duration Limits and Safety. NICE recommends Wegovy for a maximum of two years, and regulators warn about fake medicines and online prescribing.
Opportunities
- NHS Primary Care Volume. Wider GP prescribing of Mounjaro opens the largest eligible population, with Wales planning a new clinical pathway.
- Digital and Pharmacy Services. Online prescribers and pharmacies that combine medicines with coaching, monitoring and adherence support can build lasting relationships.
- Next-Generation and Oral Options. Oral and longer-acting products, including those approved elsewhere, could widen the market and reduce cold-chain costs.
- Supply Chain and Devices. Cold-chain logistics, pen devices and diagnostics support growth.
Policy and Regulatory Landscape
The Medicines and Healthcare products Regulatory Agency licenses GLP-1 medicines, which are prescription-only medicines, and the General Pharmaceutical Council regulates the online and retail pharmacies that dispense them. NICE sets NHS eligibility: a BMI of at least 35 plus at least one weight-related condition, usually reduced by 2.5 for people from certain South Asian, Chinese, Middle Eastern, Black African and African-Caribbean backgrounds. NICE recommended Mounjaro in December 2024 for GPs and specialist services, and recommends Wegovy for up to two years. Health policy is devolved, so Wales, Scotland and Northern Ireland set their own pathways.
Segment Insights
By Molecule, semaglutide led early volumes while tirzepatide is gaining share through its NHS recommendation. The full report quantifies every segment; the highlights below cover Channel and Route of Administration.
By Channel
Private online and retail pharmacies hold most revenue in 2025, with typical monthly costs of USD 198-330 (GBP 150-250) and consultation fees sometimes charged separately. NHS specialist services supply Wegovy and Saxenda, and NHS primary care is the fastest-growing channel as GPs begin prescribing Mounjaro to prioritized groups. Our analysis expects the NHS share of volume to rise through 2031F while private pricing falls.
By Route of Administration
- Injectable. Weekly pens, including Wegovy and Mounjaro with doses titrated over several months, account for the market in 2025.
- Oral. An emerging segment, following approval of an oral GLP-1 for weight loss in the US in December 2025.
Geographic Insights
Access differs across the four nations because health policy is devolved.
- England. The largest market, with NHS primary care prescribing of Mounjaro to prioritized groups from June 2025 and the densest private pharmacy network.
- Scotland. Sets its own NHS pathway, with private online demand similar to England.
- Wales. The Welsh Government confirmed plans for a new clinical pathway in October 2025, with no date set for GP access.
- Northern Ireland. A smaller market that relies more on private supply while NHS access develops.
Competitive Landscape
Key participants include Eli Lilly, Novo Nordisk, Boots, Superdrug, Asda Online Doctor, Medino, Pharmacy2U and LloydsPharmacy Online Doctor. Competition is shaped by manufacturer supply and pricing, pharmacy reach, clinical safeguards and customer service. Pharmacies compete on price, bundled consultations and aftercare, and prescribers must be UK-registered and pharmacies registered with the General Pharmaceutical Council.
Eli Lilly | Novo Nordisk | Boots | Superdrug |
Asda Online Doctor | Medino | Pharmacy2U | LloydsPharmacy Online Doctor |
Key Developments, 2024-2026
- December 2024. NICE recommends Mounjaro for prescribing by GPs as well as specialist services, with access phased over 12 years.
- March 2025. An estimated 1.5 million people in the UK use weight-loss medication.
- June 2025. Mounjaro becomes available in NHS England primary care to prioritized groups.
- October 2025. The Welsh Government confirms plans for a new clinical pathway for weight-loss medicines.
What This Means for Decision-Makers
- Manufacturers: Balance list prices against volume and NHS access as unit prices fall.
- Pharmacies and Prescribers: Invest in safeguards, adherence support and cold-chain quality to defend margin.
- NHS Planners: Build primary care capacity and wraparound services before eligibility widens.
- Investors: Underwrite on price erosion and treatment duration, not only on user numbers.
About the Report
Table 1: UK GLP-1 Weight-Loss Drugs Market: Report Coverage
Coverage Area | What the Report Covers |
Market Size and Forecast | Revenue (USD Billion) and User Views, 2021-2031F |
Segmentation | Molecule, Channel, Route of Administration and Nation |
Geography | England, Scotland, Wales and Northern Ireland |
Competition | Manufacturers, Pharmacies, Online Prescribers and Pipeline Tracking |
Policy and Pricing | MHRA Licensing, NICE Guidance, Devolved Pathways and Price Moves |
Outlook and Recommendations | White-Space Assessment and Guidance by Stakeholder |
Source: Neargoal Consulting Analysis | |
The research report, UK GLP-1 Weight-Loss Drugs Market Outlook 2021-2031F - Market Size, Share, Trends, Opportunities, and Competitive Analysis - Segmented by Molecule (Semaglutide, Tirzepatide, and Others); Channel (Private Online and Retail Pharmacies, NHS Specialist Services, and NHS Primary Care); Route of Administration (Injectable, and Oral); and Region, covers prescription GLP-1 medicines dispensed for weight management in the UK through private and NHS channels, with a 2025 base year, a 2026E estimate and a 2027F-2031F forecast. It excludes medicines for type 2 diabetes alone, orlistat and other non-GLP-1 treatments, and unlicensed or counterfeit products. Market estimates and projections are based on Neargoal Consulting’s proprietary research methodology, exhaustive primary and secondary research.
For questions about report coverage, methodology, suitability, etc.
For requirements beyond the published report