
UAE Data Center Market Outlook 2021-2031F
Market Size, Share, Trends, Opportunities, and Competitive Analysis - Segmented by Component (IT Infrastructure, Power and Cooling, and Facilities and Services); Facility Type (Hyperscale and Colocation, Enterprise, and Edge); End User (Cloud and Technology, Government and Public Sector, and Financial Services and Others); and Region
UAE Data Center Market to Reach USD 5.8 Billion by 2031, Growing at a 33% CAGR: How AI Campuses, Sovereign Cloud and Hyperscaler Commitments Are Redrawing Capacity
UAE Data Center Market Overview
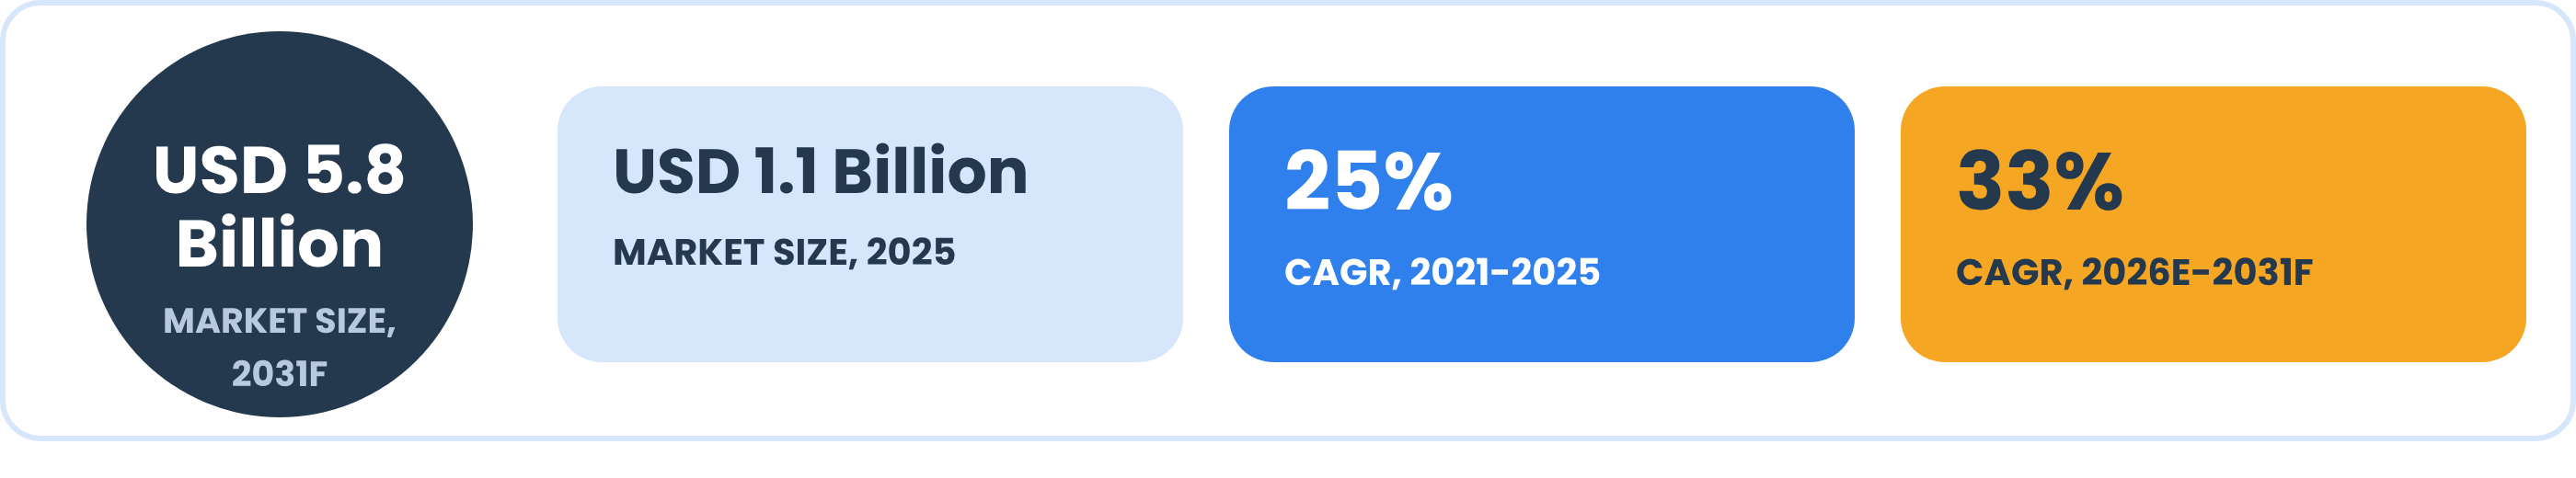
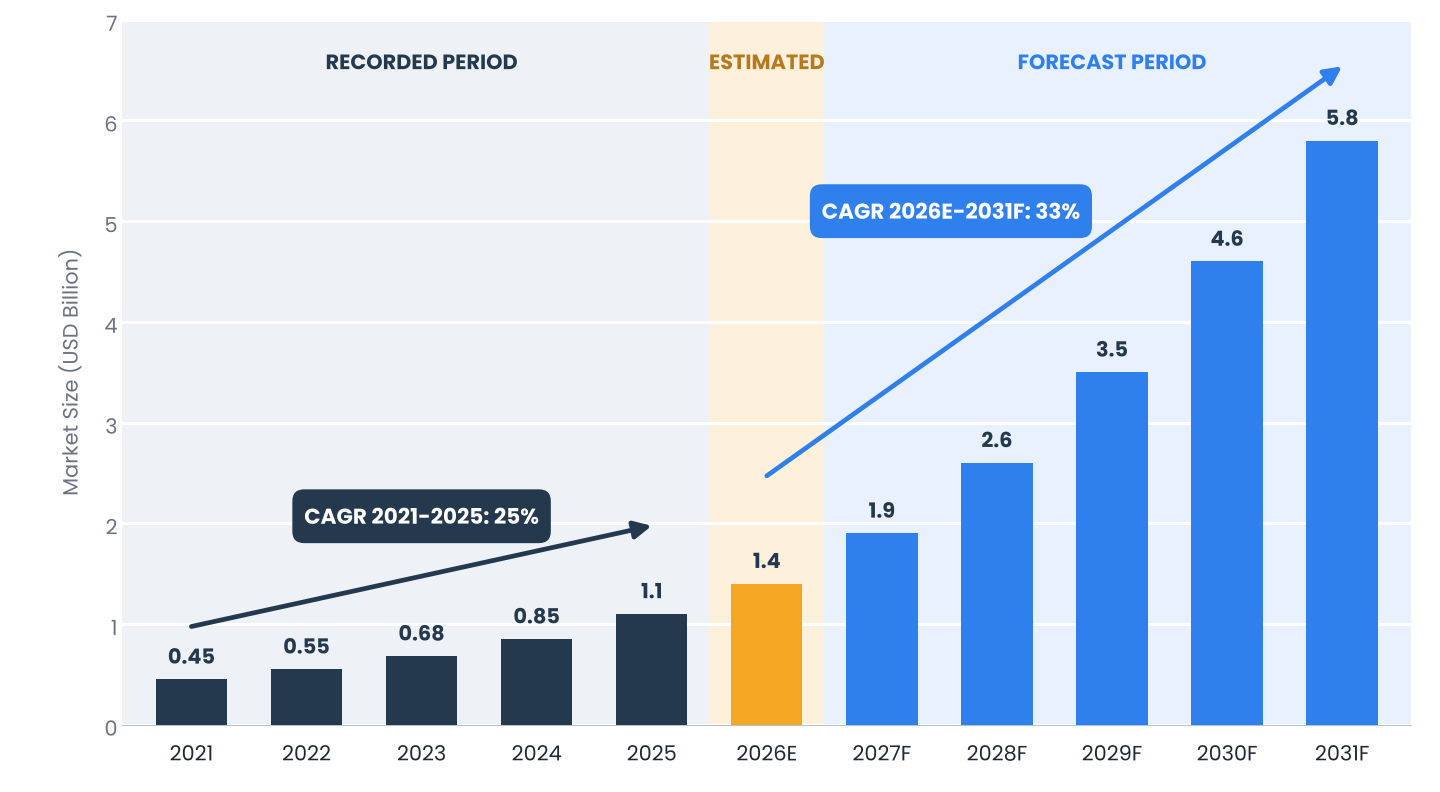
The UAE is building one of the largest concentrations of AI-ready data center capacity outside the US. Neargoal Consulting estimates the market at about USD 1.1 billion in 2025, rising to USD 1.4 billion in 2026E and USD 5.8 billion by 2031, a 33% CAGR over 2026E-2031F, after a 25% CAGR over 2021-2025. Stargate UAE is planned as a 1 GW cluster and the first phase of a 5 GW Abu Dhabi campus, Khazna Data Centers targets more than 1 GW of hyperscale capacity by 2030, and Microsoft has committed USD 15.2 billion to the country.
Key Takeaway Announced gigawatts are not usable capacity. Power connections, chip export approvals and cooling decide how fast capacity energizes, so operators that secure grid supply and accelerator allocations first will win the early AI workloads. |
UAE Data Center Market at a Glance
MARKET DEFINITION Value of Data Center Infrastructure Investment and Colocation and Hosting Revenue in the UAE (USD Billion) | ||
BASE YEAR / ESTIMATED YEAR 2025 / 2026E | FORECAST PERIOD 2027F-2031F | |
MARKET SIZE, 2025 USD 1.1 Billion | MARKET SIZE, 2026E USD 1.4 Billion | |
MARKET SIZE, 2031F USD 5.8 Billion | RECORDED CAGR, 2021-2025 25% | |
FORECAST CAGR, 2026E-2031F 33% | MICROSOFT TOTAL UAE COMMITMENT USD 15.2 Billion, Including USD 7.9 Billion for 2026-2029 | |
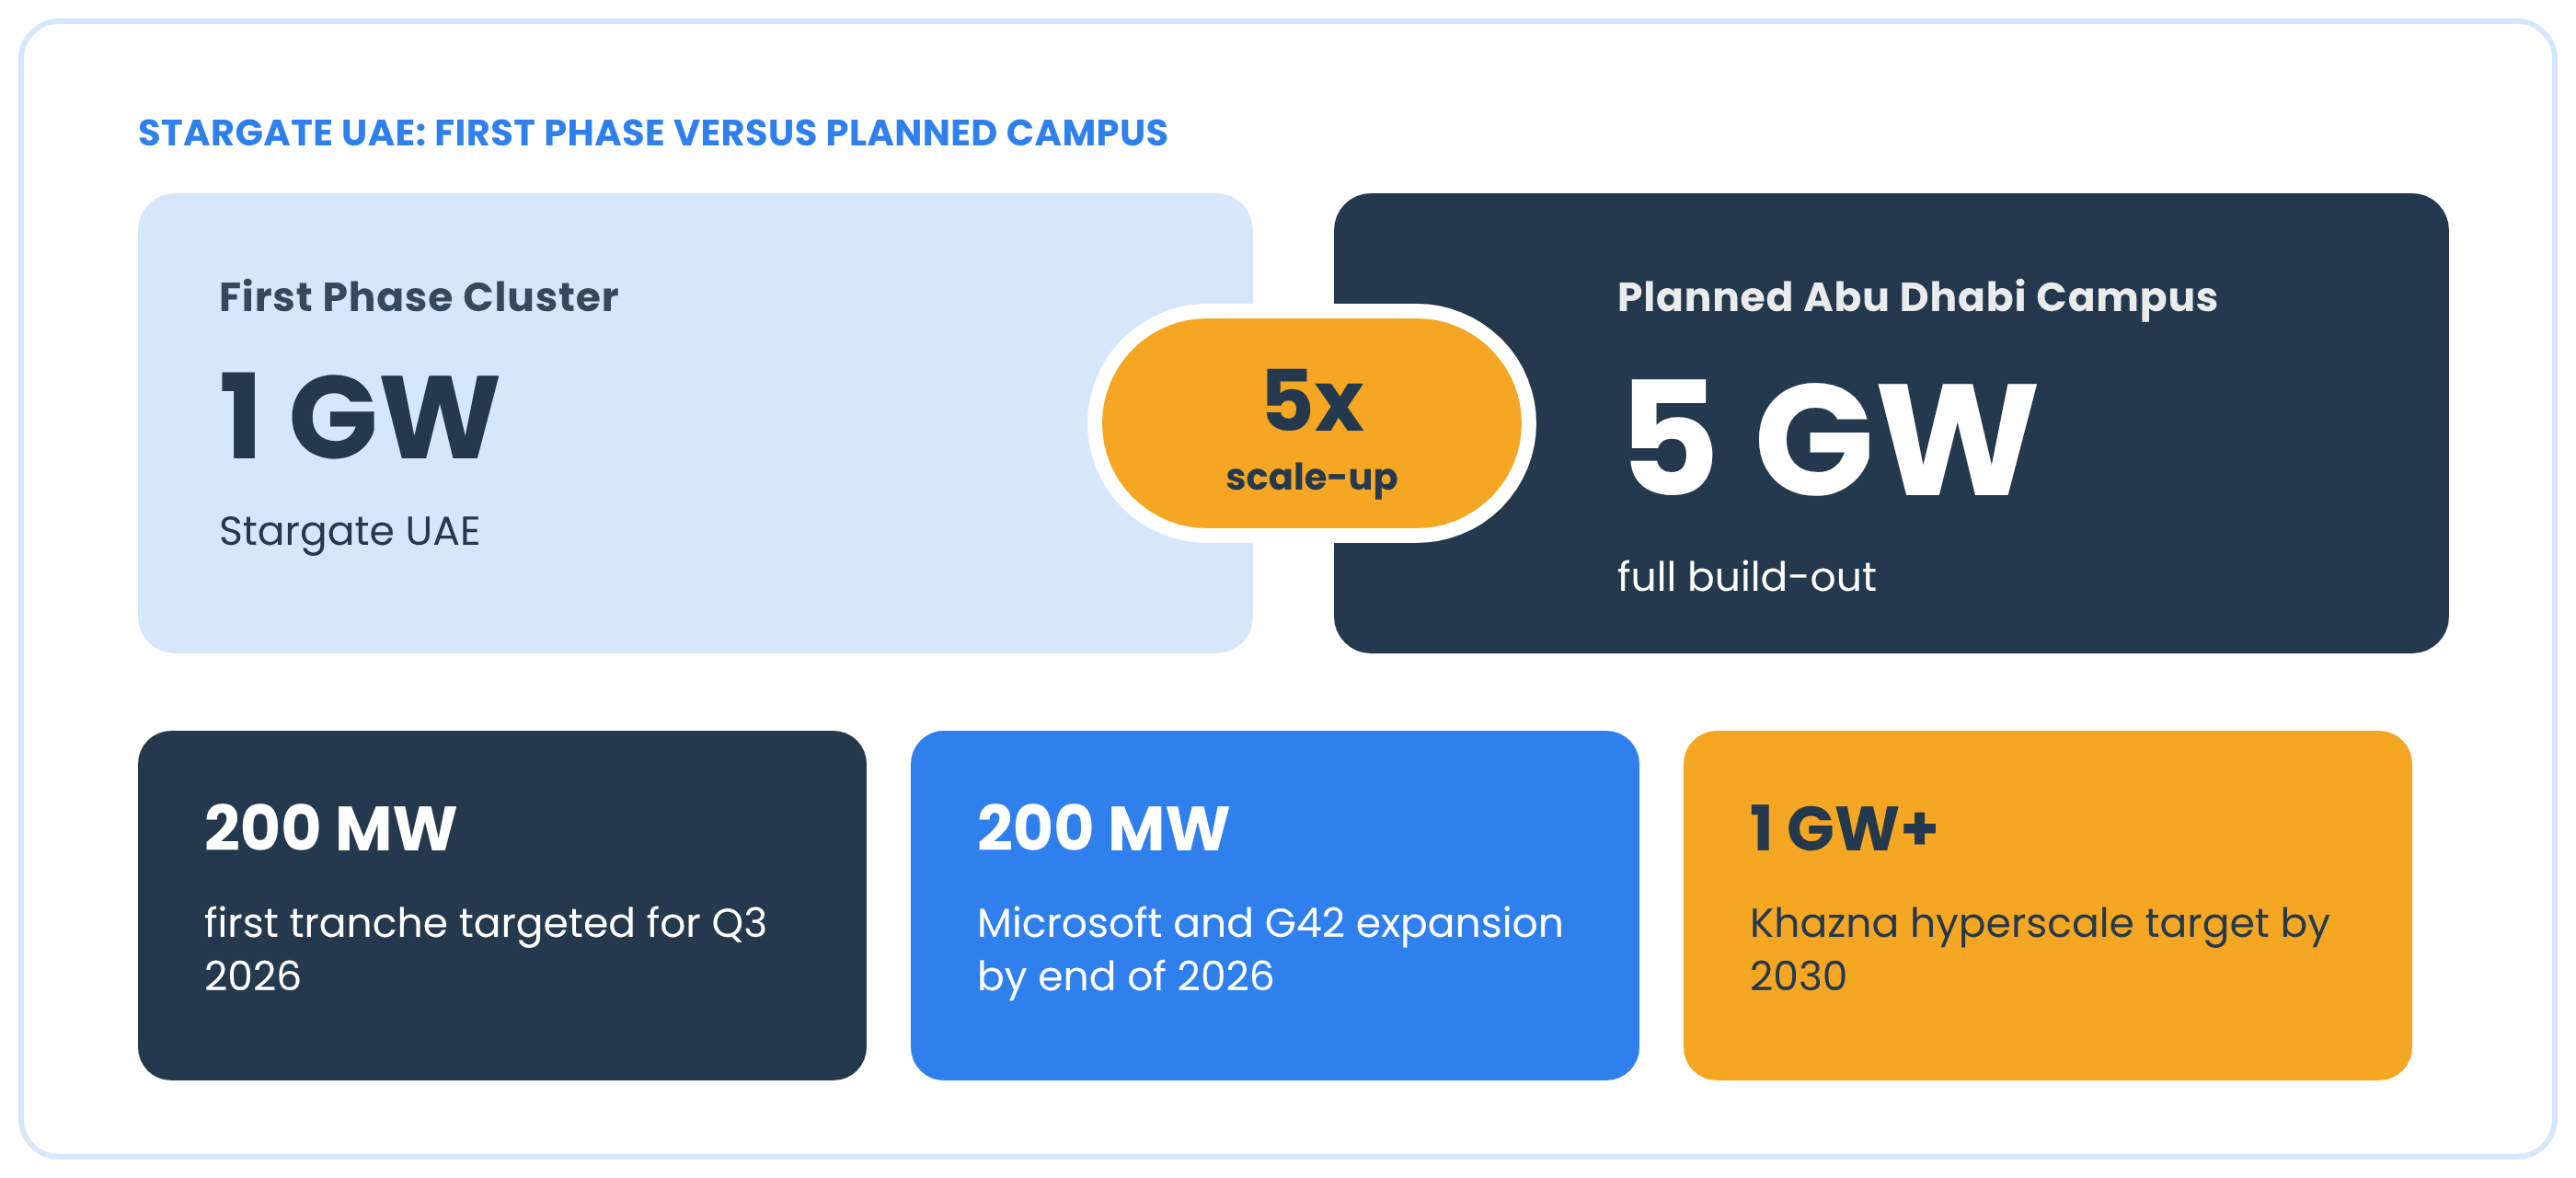
MICROSOFT AND G42 EXPANSION 200 MW, Expected Before End of 2026 | STARGATE UAE 1 GW Cluster, First Phase of a Planned 5 GW Campus | |
KHAZNA HYPERSCALE TARGET More Than 1 GW by 2030 | LEADING FACILITY TYPE Hyperscale and Colocation | |
FASTEST-GROWING SEGMENT AI-Ready Hyperscale Capacity | KEY CONSTRAINTS Power, Chip Allocation and Cooling Water | |
Source: Neargoal Consulting Analysis | ||
Market Outlook
Our study estimates the market will grow at a 33% forecast CAGR (2026E-2031F) from USD 1.4 billion in 2026E, after a 25% CAGR over 2021-2025. The base case assumes the first 200 MW tranche of Stargate UAE and the 200 MW Microsoft and G42 expansion energize through 2026E-2027F, with large campus phases following from 2028F as power and chips are secured. New capacity typically arrives in 100-200 MW increments, and AI training racks draw more than 100 kW, against 5-10 kW for traditional enterprise racks.
Figure 1: UAE Data Center Market Size, 2021-2031F (USD Billion)
Source: Neargoal Consulting Analysis
Market Dynamics
Growth Drivers
- Hyperscaler and AI Campus Commitments. Microsoft committed USD 7.9 billion for 2026-2029, bringing its UAE total to USD 15.2 billion, and Stargate UAE is planned as a 1 GW cluster within a 5 GW campus.
- Sovereign Cloud and Data Residency. A 2023 partnership set up a sovereign cloud platform hosted in Khazna data centers, and Federal Decree-Law 45 of 2021 sets a baseline for where workloads may legally run.
- State-Backed Developers. Khazna operates 30 data centers, unveiled a 1 GW expansion plan in October 2025 and has investment from MGX and Silver Lake.
Restraints
- Power and Grid Interconnection. Capacity arrives in 100-200 MW steps gated by grid interconnection and generation, so energization dates matter more than announcements.
- Chip Allocation and Export Approvals. Accelerators are policy-shaped and scarce. Microsoft received export licenses for chips equal to 60,400 additional A100s, including Nvidia GB300 GPUs.
- Cooling and Water. A forecast puts Gulf Cooperation Council data center water demand at 426 billion liters a year by 2030, which pushes operators toward direct liquid cooling.
Opportunities
- AI-Ready Hyperscale Capacity. Liquid-cooled halls for GB300-class systems serve model developers and cloud providers.
- Sovereign and Government Workloads. Public-sector and regulated workloads must stay in-country, which favors local operators.
- Power, Cooling and Construction Supply. Electrical gear, liquid cooling and modular construction see sustained demand.
- Regional Hub Role. Regional third-party capacity of about 500 MW is forecast to reach about 1.5 GW by 2030, and the UAE is positioned to serve neighboring markets.
Policy and Regulatory Landscape
The UAE’s federal data baseline is Federal Decree-Law 45 of 2021 on personal data protection, which shapes where workloads can run, and sovereign cloud arrangements set rules for government data. Export licenses from the US govern the supply of advanced accelerators to UAE operators, and Microsoft was the first company to receive licenses for additional chips of this kind. Emirate-level planning and utility approvals govern sites and power connections. The full report assesses how data, export and energy rules affect timing and cost.
Segment Insights
The full report quantifies every segment; the highlights below cover Component, Facility Type, and End User.
By Component
IT infrastructure takes the largest share of spending, while power and cooling grow fastest with rack density.
By Facility Type
Hyperscale and colocation facilities hold most revenue in 2025 and are expected to widen their lead as AI campuses energize. Enterprise facilities serve banks, government and industry that keep systems in-house, while edge facilities are small and serve low-latency needs. Our analysis expects hyperscale capacity to account for most added megawatts through 2031F.
By End User
- Cloud and Technology. Hyperscalers, model developers and technology groups, the largest buyers of capacity.
- Government and Public Sector. Sovereign cloud and national AI programs.
- Financial Services and Others. Banks, telecom operators and industrial users.
Geographic Insights
Capacity concentrates in Abu Dhabi, where the largest campuses are planned, and in Dubai, the established connectivity hub.
Figure 2: Stargate UAE: First Phase Versus Planned Campus Capacity
Source: Neargoal Consulting Analysis
- Abu Dhabi. Hosts the planned 5 GW Stargate UAE campus and Khazna’s largest developments.
- Dubai. Home to Microsoft’s UAE cloud region, launched in 2019 with three availability zones, and Khazna’s DXB8 facility.
- Sharjah and Northern Emirates. Smaller sites tied to enterprise and edge needs.
Competitive Landscape
Key participants include Khazna Data Centers, G42, Microsoft, OpenAI, Nvidia, e&, MGX and Silver Lake. Competition rests on power access, accelerator supply and the speed of energization. Khazna became the UAE’s largest data center provider after combining G42 and e& data center operations in October 2021, and in April it broke ground on two data centers totaling 60 MW due through 2026.
Khazna Data Centers | G42 | Microsoft | OpenAI |
Nvidia | e& | MGX | Silver Lake |
Key Developments, 2025-2026
- October 2025. Khazna unveils a 1 GW expansion plan.
- November 2025. Microsoft and G42 announce a 200 MW expansion through Khazna, expected before the end of 2026, as part of a USD 7.9 billion investment for 2026-2029.
- 2026. Stargate UAE targets its first 200 MW tranche, as the first phase of a 1 GW cluster within a planned 5 GW campus.
- April. Khazna breaks ground on two data centers totaling 60 MW, due for completion through 2026.
What This Means for Decision-Makers
- Operators: Contract against energization dates and secure accelerator allocations early.
- Cloud Users: Classify workloads by where they can legally run before choosing capacity.
- Equipment Suppliers: Prepare for liquid cooling and high-density power as standard.
- Investors: Track energized megawatts, not announced gigawatts.
About the Report
Table 1: UAE Data Center Market: Report Coverage
Coverage Area | What the Report Covers |
Market Size and Forecast | Revenue (USD Billion) and Capacity (MW) Views, 2021-2031F |
Segmentation | Component, Facility Type, End User and Emirate |
Geography | Abu Dhabi, Dubai, Sharjah and Northern Emirates |
Competition | Operators, Hyperscalers, Chip Suppliers and Capacity Tracking |
Policy and Constraints | Data Law, Export Licenses, Power and Water |
Outlook and Recommendations | White-Space Assessment and Guidance by Stakeholder |
Source: Neargoal Consulting Analysis | |
The research report, UAE Data Center Market Outlook 2021-2031F - Market Size, Share, Trends, Opportunities, and Competitive Analysis - Segmented by Component (IT Infrastructure, Power and Cooling, and Facilities and Services); Facility Type (Hyperscale and Colocation, Enterprise, and Edge); End User (Cloud and Technology, Government and Public Sector, and Financial Services and Others); and Region, covers data center infrastructure investment and colocation and hosting revenue in the UAE, with a 2025 base year, a 2026E estimate and a 2027F-2031F forecast. It excludes public cloud service revenue, network operator infrastructure and data centers outside the country. Market estimates and projections are based on Neargoal Consulting’s proprietary research methodology, exhaustive primary and secondary research.
For questions about report coverage, methodology, suitability, etc.
For requirements beyond the published report